
A condo may look like the right fit, but the building’s financial profile can affect your mortgage options. Financing a condo in Key Largo involves more than reviewing your own finances. A lender may also assess the condominium association and the property’s lending profile.
If you’re wondering how to buy a condo in Key Largo, account for that extra layer early. Consider your budget and borrower profile, compare loan options, and learn what a lender may review about the association’s finances, insurance, reserves, and maintenance plans. Knowing what to prepare can help you identify questions before they become surprises.
This guide covers the main financing stages, the buyer and building details lenders may evaluate, and how local buyer representation can connect your financing readiness with a condo search. Whether you’re looking in Key Largo, Islamorada, Tavernier, or elsewhere in the Upper Keys, a practical plan can help you move forward with greater confidence.
Key Takeaways
- Condo financing considers both your qualifications and the specific property’s lending profile, so prepare for both parts of the review.
- Learn how to buy a condo in Key Largo by comparing broad loan pathways and discussing eligibility with a loan professional.
- Organize your financial records before applying, then follow the lender’s guidance on which documents are needed.
- For help with your local search, reach out to Krissy with questions or requests for clarification, or ask for a list of current homes on the market.
Why a Key Largo Condo Mortgage Involves More Than Your Personal Finances
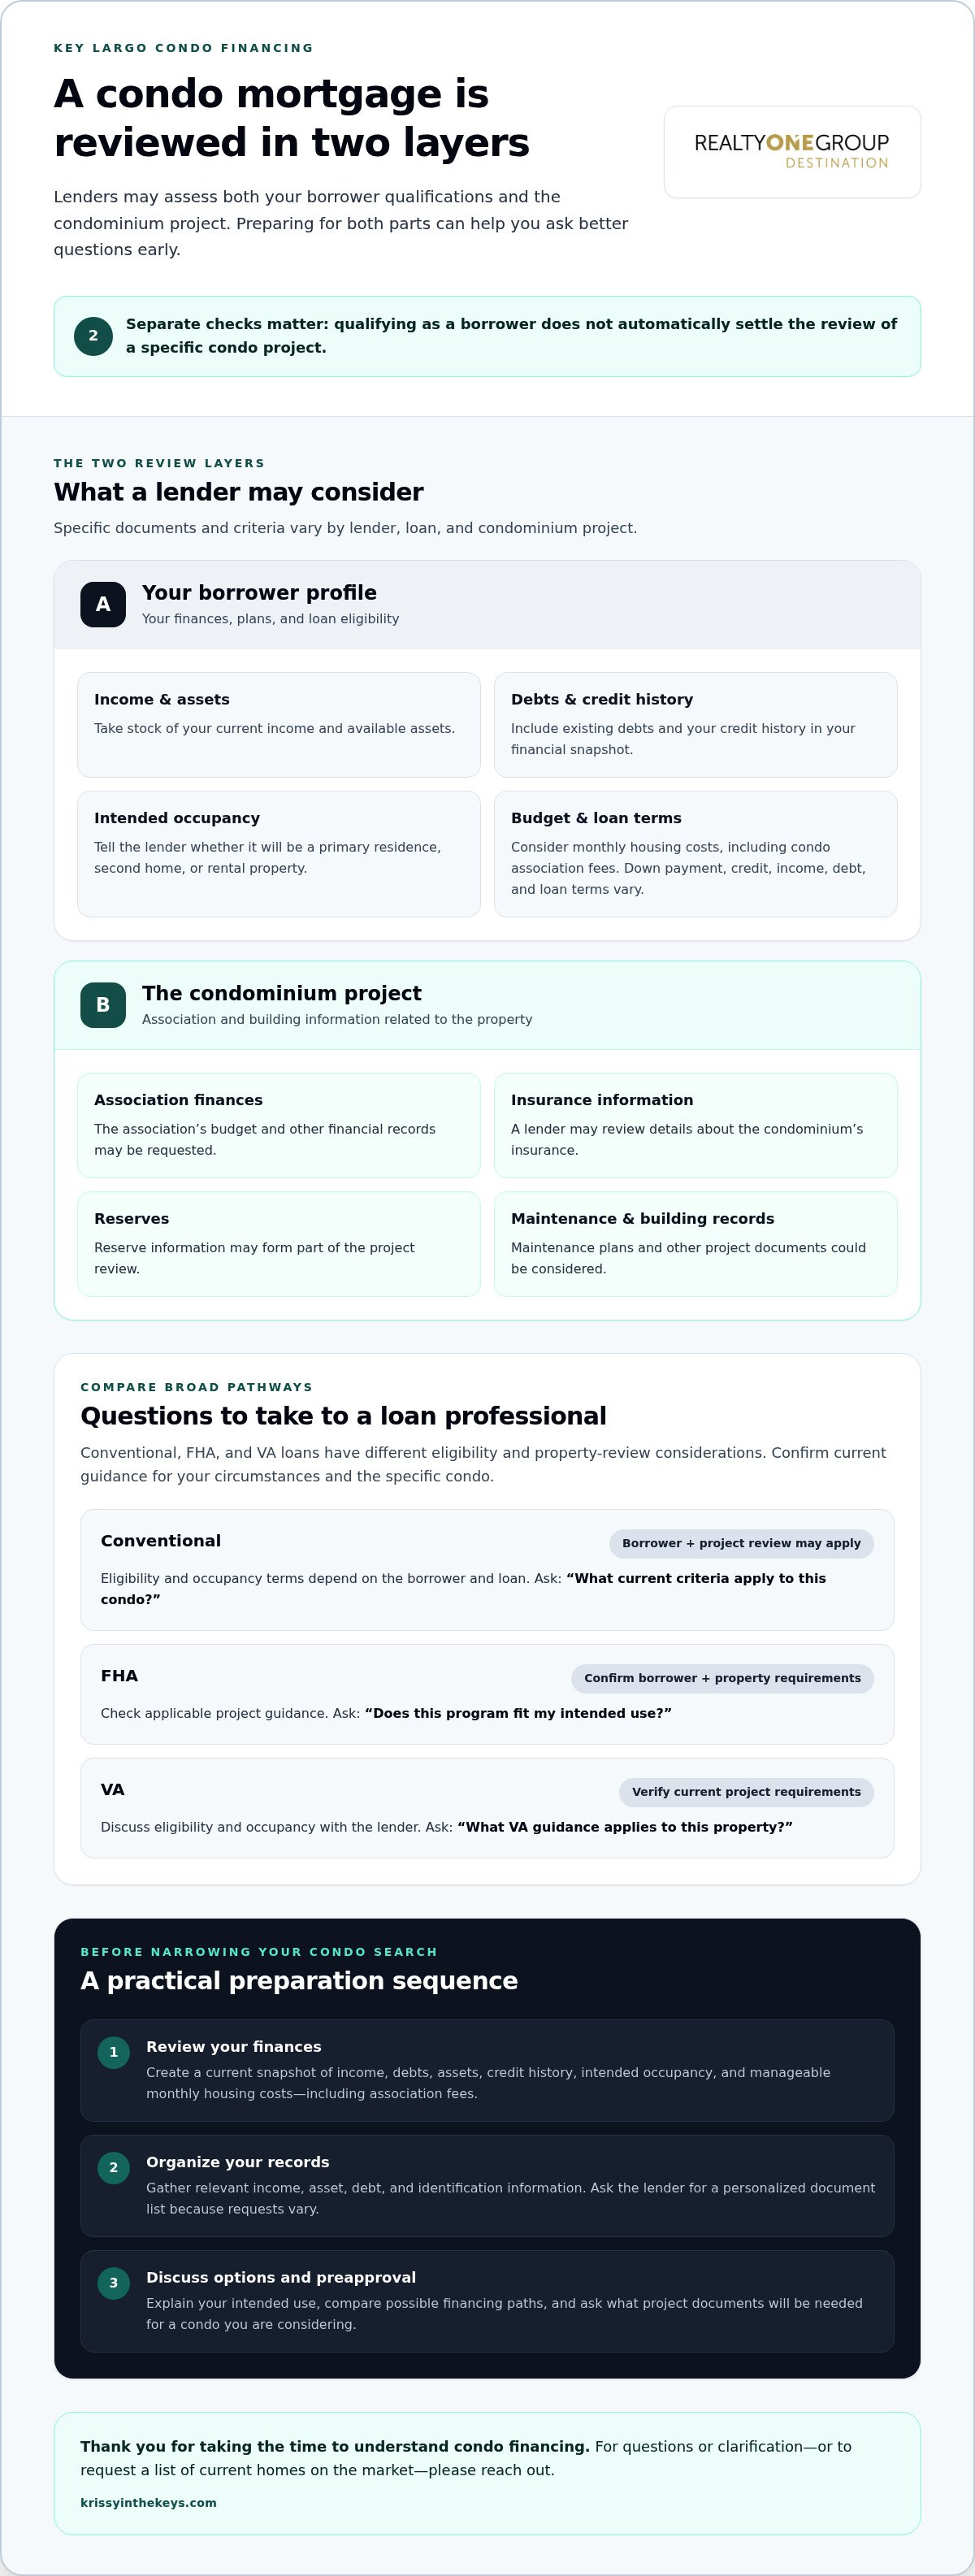
Understanding how to buy a condo in Key Largo means looking beyond your income, assets, and credit profile. Condo financing can involve a review of both the borrower and the property or condominium project. A lender may request association records or building information as part of its assessment. The documents and criteria vary by loan and lender, so one project’s experience does not predict another’s.
A condominium combines ownership of an individual unit with shared interests in common areas. That structure helps explain why a lender may consider details beyond the unit itself. A condo mortgage review can examine both the buyer’s qualifications and the condominium project, while a typical single-family review focuses on the borrower and the individual property. This guide focuses on financing a condo purchase, not general home-buying advice or an investment strategy.
What can make condo financing different from a house mortgage?
Alongside your application, a lender may seek information about the association and building. Records could include the association’s budget, insurance details, reserve information, maintenance plans, or other project documents. These materials help the lender assess the condominium. Requirements vary, and no single project rule or approval outcome applies to every loan. Discuss the specific property with your loan professional early, before you build your plans around one unit.
Which Key Largo purchase goals should shape your financing plan?
Start by deciding whether you plan to use the condo as a primary residence, a second home, or a rental property. These are distinct purchase scenarios, and intended use can affect which financing options are worth discussing. Describe your plans accurately to the lender, including any rental intentions. Don’t assume a vacation property will be treated like a primary home. If you’re considering buying a vacation home in Key Largo, include that goal in your first financing conversation.
As you clarify your plans, consider how the condo’s ongoing costs fit your budget alongside the mortgage. This gives you a more useful starting point for comparing properties in Key Largo, Islamorada, Tavernier, and the wider Upper Keys.
Compare Condo Mortgage Options and Understand What Lenders May Review
Once you know how you plan to use the condo, compare broad financing pathways with a loan professional or mortgage brokerage like Smart Home Loans. Conventional, FHA, and VA loans each have their own eligibility and property-review considerations, and program guidance can change. Ask how the option you’re considering applies to both your finances and the specific condominium project.
Project eligibility and borrower qualification are separate parts of condo financing. You may meet a loan program’s borrower criteria while a particular condominium still requires additional review. Fannie Mae, Freddie Mac, FHA, and the U.S. Department of Veterans Affairs provide program guidance. Ask your loan professional to verify the current criteria that apply to your loan and the property.
How does intended occupancy affect a condo mortgage discussion?
Tell the lender whether you plan to live in the condo as your primary residence, use it as a second home, or rent it. These are different scenarios, and lenders may assess occupancy differently. If you’re planning a Key Largo getaway, explain your intended use and any rental plans, then confirm how they affect the financing options available to you. For real estate investors pursuing rental opportunities who need flexible capital, private lenders like Level 4 Funding offer tailored loan programs designed for investment purchases.
What building and association information may lenders consider?
Depending on the loan and project, review materials may include association financial records, insurance information, and other details about the building or condominium. Requirements vary. Once you have a property in mind, ask the lender what documents it will need for that specific condo.
| Pathway | Occupancy and borrower eligibility | Possible project review | Ask your loan professional |
|---|---|---|---|
| Conventional | Eligibility and occupancy terms depend on the borrower and loan. | Project review may apply. | What current criteria apply to this condo? |
| FHA | Confirm borrower and property requirements for your situation. | Check applicable project guidance. | Does this program fit my intended use? |
| VA | Discuss eligibility and occupancy with the lender. | Verify current project requirements. | What VA guidance applies to this property? |
Down payment, credit, income, debt, and loan terms vary by borrower and lender. As you consider how to buy a condo in Key Largo, Krissy can help connect your financing readiness with a local condo search. Explore current condo listings in Key Largo and the Upper Keys, or get in touch with questions and requests for clarification.
How to Prepare and Apply for a Key Largo Condo Mortgage
A clear sequence can make financing easier to manage. As you plan how to buy a condo in Key Largo, take stock of your finances and speak with a lender before narrowing your property search.
- Review your finances. Make a current snapshot of your income, debts, assets, credit history, and intended occupancy. Consider what monthly housing costs feel manageable, including the condo’s association fees.
- Organize your records. Gather relevant income, asset, debt, and identification information. Document requests vary, so ask the lender for a personalized list instead of assuming every application requires the same paperwork.
- Discuss loan options and preapproval. Share your intended use for the condo and ask which financing paths may fit your circumstances. A preapproval discussion can help establish practical search parameters, but it isn’t a guarantee of final approval.
- Choose a property and apply. Once you identify a condo, coordinate with the lender about the application and any property or association information needed for review. Keep the lender updated as the purchase progresses.
Final financing depends on the lender’s review of both the buyer’s qualifications and the property’s details. Preapproval is a planning tool, and the lender still needs to assess the specific transaction. Keep your loan professional informed as your search moves from broad preferences to a particular Key Largo condo.
Krissy Carnahan represents buyers in Key Largo and the Upper Keys, including first-time buyers and vacation property investors. She can help you evaluate available properties and navigate offer discussions while you coordinate financing directly with your lender. This can keep your property search and financing conversations aligned as you compare condos in Key Largo, Islamorada, and Tavernier.
View active Key Largo condo and home listings
Move From Mortgage Preparation to a Key Largo Condo Purchase
Financing preparation gives you a starting point, not the whole path. A steady process can help you move from an initial lender conversation to an informed offer while keeping the lender involved as the property details become clear.
- Discuss your plans with the lender. Review your intended use and financing questions so you understand the next steps for your situation.
- Search with your priorities in mind. Focus on condos that fit your lifestyle and the practical parameters discussed with the lender.
- Coordinate a project review. Once you’re interested in a specific condo, ask the lender what property or association information is needed and how to proceed.
- Plan your offer. Consider the property’s fit and your financing timeline as you prepare offer terms and negotiate.
- Keep communication open. Share relevant updates with the lender as the transaction progresses, and follow its guidance on remaining financing steps.
How can local buyer representation support your next steps?
Local representation can help you understand condo options, assess how a property fits your goals, and navigate offer discussions. Krissy Carnahan represents buyers in Key Largo and the Upper Keys, bringing local market knowledge and negotiating experience to your search. You can explore active Key Largo condo and home listings as you refine your priorities in Key Largo, Islamorada, or Tavernier.
What should you do if a lender raises a concern about a condo?
Ask which specific borrower or project information needs clarification and what the lender needs next. The right next step depends on the lender’s requirements and the property. Krissy can help you consider local property questions and offer discussions, while the lender remains responsible for financing decisions.
With a clear plan and informed local representation, you can approach how to buy a condo in Key Largo one decision at a time. Reach out to Krissy with questions or requests for clarification, or ask for a list of current homes available on the market.
Take Your Next Step Toward a Key Largo Condo
A condo purchase becomes more manageable when you turn what you’ve learned into a conversation about your goals, timing, and preferred way of life. If you’re still weighing options, that’s a useful place to begin. A clear picture of how to buy a condo in Key Largo can help you move from research toward a search that feels right for you.
Krissy Carnahan is a licensed Florida Realtor focused on Key Largo and the Upper Keys, including Islamorada and Tavernier. She represents buyers, including first-time purchasers and vacation property investors, and brings negotiating experience to the process. Lender decisions remain with the lender, while local buyer representation can help you assess property fit and plan your next move.
Thank you for considering Krissy as a resource for your Key Largo condo search. Please get in touch with any questions or requests for clarification, or to receive a list of current homes available on the market.
Frequently Asked Questions
Is it harder to get a mortgage for a condo than for a house?
Not necessarily. A condo mortgage isn’t automatically harder to obtain than a house mortgage, but a lender may need information about the condominium as well as your application. For a useful comparison, discuss the same intended occupancy and purchase scenario with your lender, and ask what property-specific review may involve before you focus on one unit.
Can I get a mortgage for a Key Largo condo I plan to use as a vacation home?
It may be possible, but options depend on your finances, intended use, lender, loan program, and property. Explain how you plan to use the condo, including whether you also expect to rent it. Be accurate rather than describing it as a primary residence if that isn’t your plan. Clear details help the lender discuss terms for your situation.
How much down payment do I need to buy a condo in Key Largo?
There isn’t one down-payment amount that applies to every buyer. Your figure may depend on the loan program, occupancy, borrower profile, lender requirements, and property. Ask lenders to outline the down-payment options for your circumstances alongside the expected payment, cash needed at closing, and other loan terms. Comparing those details makes it easier to understand the costs associated with each option.
Can a condo mortgage be declined because of the condominium association or building?
Yes, association or building information may affect a lender’s review, but a concern doesn’t automatically mean every financing option is unavailable. Ask which specific item prompted the concern, whether additional information could address it, and what options the lender sees for that property. The answer depends on the condo and the lender’s requirements, so seek guidance tied to your situation.
Can rental income help me qualify for a Key Largo condo mortgage?
Possibly, but don’t count on projected rent qualifying you until the lender explains how it treats that income. Describe whether you plan to use the condo as a second home or rental, and ask what records or assumptions apply. For example, ask whether documented rental history is relevant to your application. Avoid building your budget around future income the lender hasn’t said it can consider.
Thank you for reading. Get in touch with questions or requests for clarification about your search in Key Largo, Islamorada, Tavernier, or the Upper Keys. Krissy can also provide a list of current homes available on the market.


